Every week I hear from homeowners who say something like:"Brook, I got a letter in the mail offering to buy my house for cash. It seems easy... should I do it?"Sometimes the answer is yes.But many

Dated: March 16 2026
Views: 81
Published: March 16, 2026
Source referenced: The New York Times, March 9, 2026
Article: The Hidden Factor Behind Your Home Insurance Cost: Your Credit History
By: Claire Brown and Mira Rojanasakul
When most people think about the cost of homeownership, they focus on the obvious numbers: purchase price, mortgage payment, property taxes, and maybe HOA dues. But there’s another major expense that can quietly hit a lot harder than expected—homeowners insurance. And as this recent New York Times article points out, one of the biggest hidden factors affecting that cost in many states is your credit history.
That catches a lot of people off guard.
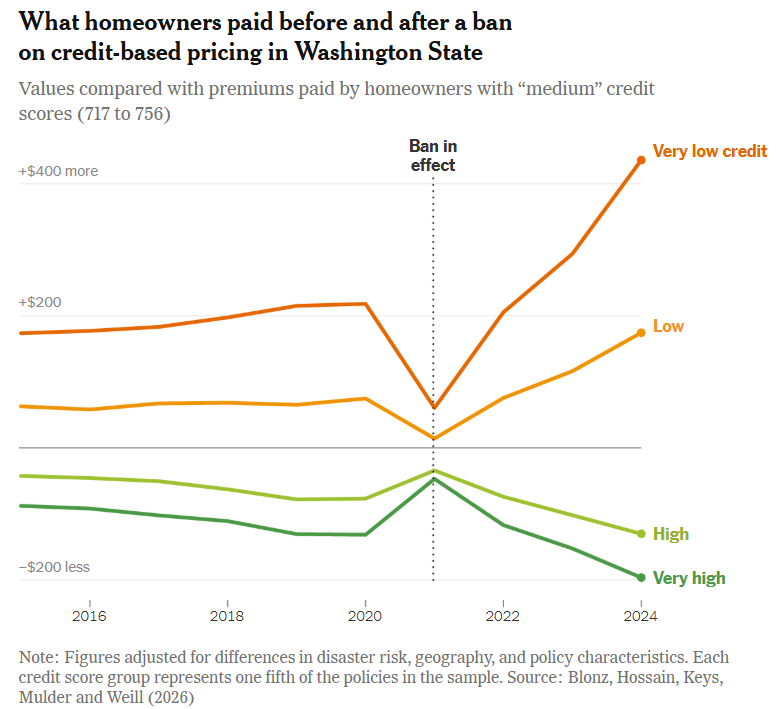
Most buyers assume insurance pricing is based mainly on the home itself—things like age of roof, location, storm exposure, fire risk, replacement cost, and prior claims. Those things absolutely matter. But in many states, insurers also use a credit-based insurance score when setting premiums. That means two people insuring very similar homes may end up with very different insurance costs simply because their financial profiles are different.
That’s a big deal, because insurance is no longer a small line item for many homeowners. It can materially affect affordability, cash flow, and even whether a buyer feels comfortable moving forward with a purchase.
If you are buying a home, especially in a market where affordability is already stretched, insurance can be the expense that tips the monthly payment from manageable to uncomfortable. And if you already own a home, rising premiums can add pressure even when your mortgage payment is fixed.
What makes this even more frustrating is that many people do not realize their credit may be affecting their insurance rates at all.
According to the New York Times piece, in states where insurers are allowed to use credit information, homeowners with weaker credit profiles often pay meaningfully more than those with excellent credit—even when the homes themselves are nearly identical. In some cases, the gap can be substantial. That means a person may be doing everything right with budgeting for a mortgage and taxes, yet still be blindsided by a much higher total monthly housing cost.
This is exactly why I encourage buyers to look beyond just the interest rate or purchase price. The real question is: What is the total monthly cost of owning this home?
That includes:
Principal and interest
Property taxes
Homeowners insurance
Flood insurance, if applicable
HOA dues, if applicable
Maintenance and reserves
If one of those numbers is out of line—especially insurance—it can change the whole equation.
A home may look affordable on paper at first glance, but if insurance comes in far above expectations, the payment picture changes fast.
The good news is this is something you can get in front of.
If you’re planning to buy, refinance, or simply want to reduce your overall housing costs, it makes sense to review the things that may influence not just your loan terms, but your insurance options as well. In many cases, a stronger credit profile can improve more than one part of the transaction.
That’s where a little planning can pay off.
I can help you:
Review your credit profile from a mortgage and affordability standpoint
Talk through practical strategies to improve your position
Identify steps that may strengthen your financing options
Connect you with trusted insurance agents in my network so you can compare coverage and pricing
Sometimes the issue is not just finding a policy. It’s finding the right strategy before you get too far down the road.
The blunt truth is this: a lot of buyers spend time obsessing over interest rates while overlooking insurance until the last minute. That’s a mistake. In today’s market, insurance deserves attention early in the process, especially in areas affected by hurricanes, wildfire risk, hail, flood concerns, or other major weather exposure.
If you understand the full picture upfront, you can make smarter decisions, avoid surprises, and put yourself in a stronger negotiating position.
The home itself is only part of the affordability equation. Your financial profile may affect not only your mortgage terms, but also what you pay to insure the property. That’s one more reason to prepare early and build a smart plan before making a move.
If you’d like help reviewing your credit, improving your buying strategy, or getting connected with reputable insurance professionals, reach out. I’m happy to help you think through the numbers before they become a problem.
Brook Swientisky
Real Estate Agent | Mortgage Broker
303.249.4262
[email protected]
Referenced article: Claire Brown and Mira Rojanasakul, The Hidden Factor Behind Your Home Insurance Cost: Your Credit History, The New York Times, March 9, 2026.
Link: https://www.nytimes.com/interactive/2026/03/09/climate/home-insurance-credit-scores.html?searchResultPosition=1
Hi, I’m Brook Swientisky! Real estate isn’t just my job—it’s been a part of my life for as long as I can remember.I help homeowners in Lone Tree and Douglas County prepare, pri....
Every week I hear from homeowners who say something like:"Brook, I got a letter in the mail offering to buy my house for cash. It seems easy... should I do it?"Sometimes the answer is yes.But many
Published: March 16, 2026Source referenced: The New York Times, March 9, 2026Article: The Hidden Factor Behind Your Home Insurance Cost: Your Credit HistoryBy: Claire Brown and Mira RojanasakulWhen
If February is any indication, the Denver market is waking up earlier than usual. We are seeing more inventory hit the market, more buyers stepping off the sidelines, and a noticeable improvement in
4 Beds + Optional Study | 3 Baths | 2,127 SF Above Grade | 3,319 Total SF | 3-Car GarageIf you’ve been waiting for a truly turn-key home in southeast Aurora, this one delivers. Thoughtfully
 Information deemed reliable but not guaranteed by the MLS. © 2026 Information and Real Estate Services, LLC.
Information source: Information and Real Estate Services, LLC. Provided for limited non-commercial use only under IRES Rules. © Copyright IRES.
The information being provided is for the consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumer may be interested in purchasing.
The IRES, LLC Data on this
site was last updated: September 27, 2026 7:25 AM UTC
This site is used and paid for by multiple independent companies. The real estate broker cannot require you as a prospective buyer to pre-qualify with or utilize the services of either of the mortgage loan originators. Nor can either of the mortgage load originators require you as a prospective buyer to utilize the services of the real estate broker.
Show More...
 The real estate listing information and related content displayed on this site is provided exclusively for consumers� personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. This information and related content is deemed reliable but is not guaranteed accurate by elevateMLS.
